How to Stop Foreclosure in Pensacola: 5 Options Before It's Too Late
Home Renovations / Posted 2 days ago by Quality Properties / 10 views / New
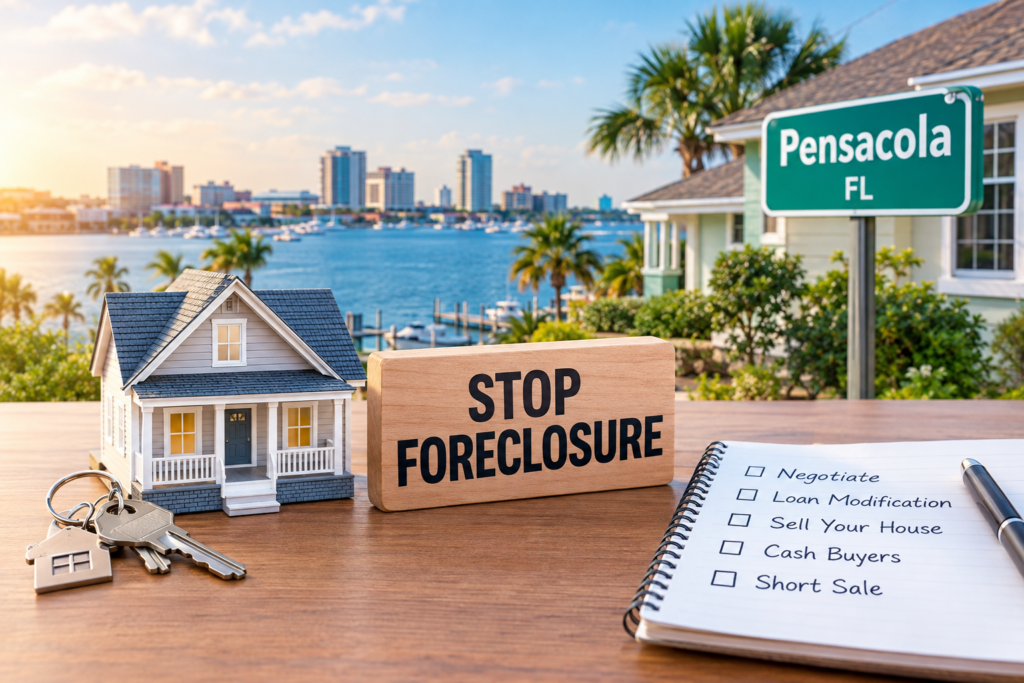
Falling behind on mortgage payments can make homeowners feel as though foreclosure is unavoidable. In reality, there may still be several ways to regain control, especially when action is taken early. If you are struggling with payments, understanding your choices can help you make a decision based on your financial situation rather than waiting until an auction date is approaching.
For some Pensacola homeowners, negotiating with the mortgage servicer may provide enough relief to keep the property. For others, selling may be the more practical solution. If keeping the house is no longer financially realistic, deciding to sell your house in Pensacola FL before the foreclosure reaches its final stages may help you protect available equity and create a cleaner path forward.
Foreclosure is a legal process through which a lender attempts to recover an unpaid mortgage debt by taking action against the property securing the loan. The important point is that homeowners should not ignore notices or stop communicating with their lender. The earlier you understand your options, the more opportunities you may have.
1. Contact Your Mortgage Servicer Immediately
The first step is often the simplest: talk to your lender or mortgage servicer. Avoiding phone calls and letters will not make the debt disappear, and delaying communication can reduce the time available to negotiate a solution.
Explain your financial hardship and ask what loss mitigation programs may be available. Depending on your circumstances and loan terms, possibilities may include a repayment arrangement, forbearance, or loan modification.
A loan modification can change certain terms of an existing mortgage, potentially making payments more manageable. Forbes Advisor explains that modifications can involve adjustments such as the loan term or interest rate.
Before agreeing to anything, request the terms in writing and make sure you understand how the arrangement affects your future payments.
2. Explore Forbearance or a Loan Modification
Temporary financial problems do not always mean that a homeowner needs to sell. If your hardship is expected to improve, mortgage forbearance could provide temporary breathing room.
Forbearance may allow qualified borrowers to pause or reduce payments for a specific period. However, the missed amount generally does not simply disappear. You need to understand how the deferred payments will be handled once the forbearance period ends.
A modification may be more appropriate when the problem is expected to continue. For example, imagine a Pensacola homeowner who experienced a permanent reduction in income and can no longer afford the original monthly payment. A modified loan with more manageable terms could potentially allow that homeowner to remain in the property.
The key is to apply early and provide the financial documentation requested by the servicer.
3. Sell Before the Foreclosure Sale
When keeping the property is no longer realistic, selling can become an important alternative. If you have enough equity, a conventional sale may allow you to pay the mortgage balance and selling expenses while potentially keeping the remaining proceeds.
The important factor is timing. A traditional listing can take time because the property may need preparation, repairs, showings, negotiations, inspections, and financing contingencies. When foreclosure deadlines are getting closer, homeowners should carefully evaluate whether that timeline fits their situation.
4. Consider a Cash Sale for a Property You Do Not Want to Repair
Some homeowners delay selling because their property needs a new roof, plumbing work, electrical repairs, storm damage restoration, or general maintenance. In a traditional sale, these issues can make preparing the property more complicated.
This is where cash home buyers in Pensacola may be worth researching. A cash buyer may purchase a property in its current condition, which can eliminate the need to spend money preparing the house for the market.
For example, consider an owner who owes $210,000 on a property that needs substantial repairs. Instead of spending another $30,000 or $40,000 preparing the house for a conventional listing, the homeowner could compare an as is cash offer with the estimated proceeds from a traditional sale.
The numbers should always be evaluated carefully. A cash offer is not automatically the highest possible price, so homeowners should compare the offer, closing costs, timeline, existing mortgage balance, and any foreclosure deadlines before making a decision.
5. Investigate a Short Sale or Other Legal Alternatives
If your property is worth less than the amount owed on the mortgage, selling for enough to completely repay the loan may not be possible. In that situation, a short sale may be an option to discuss with your lender.
A short sale generally involves selling the property for less than the outstanding mortgage balance with the lender’s approval. Because the process can involve specific requirements and potential financial consequences, homeowners should speak with their mortgage servicer and, when appropriate, a qualified real estate attorney or housing counselor.
Another possible alternative in certain situations is a deed in lieu of foreclosure, where ownership is transferred to the lender under an agreement intended to avoid the foreclosure process. The availability and consequences of these options depend on the homeowner’s circumstances and loan documents.
What Should You Do If the Foreclosure Sale Is Already Scheduled?
A scheduled foreclosure sale means time is especially important. Do not assume that nothing can be done. Contact your lender immediately and determine the exact status of the case, amount required to bring the loan current, and deadline for any available resolution.
At the same time, speak with a qualified professional who can explain your legal and financial options. If selling the property is the preferred solution, determine whether a sale can realistically close before the scheduled date.
Every situation is different. The amount owed, property value, available equity, lender requirements, and foreclosure timeline can all change which option makes the most sense.
Conclusion
Foreclosure can feel overwhelming, but homeowners in Pensacola may have several options before losing their property. Contacting the mortgage servicer, exploring loan modification or forbearance, pursuing a traditional sale, considering cash home buyers in Pensacola, or investigating a short sale may provide possible paths forward.
If keeping the home is no longer financially practical, acting early can give you more time to compare your choices. Homeowners who need a faster solution can also explore whether they can sell your house in Pensacola FL through a direct cash sale.
FAQs
Can I sell my house in Pensacola FL if foreclosure has already started?
In some situations, homeowners may still be able to sell before the foreclosure sale is completed. However, the available time depends on the specific stage of the process, so contact your lender and qualified professionals immediately.
How can I stop foreclosure in Pensacola without selling my home?
You may be able to explore options such as loan modification, forbearance, repayment arrangements, or other loss mitigation programs with your mortgage servicer. Eligibility depends on your circumstances and loan terms.
Can cash home buyers in Pensacola help with a foreclosure?
A cash buyer may be able to purchase a property before the foreclosure sale, depending on the timeline and property circumstances. The transaction must move quickly enough to meet applicable deadlines.
Can I sell a house in Pensacola that needs major repairs before foreclosure?
Yes, a property does not necessarily have to be fully renovated before you explore selling it. Some cash buyers purchase homes in as is condition, allowing homeowners to avoid making extensive repairs.
What happens if my Pensacola house is worth less than my mortgage?
If the property’s market value is below the outstanding mortgage balance, you may need to discuss a short sale or another solution with your lender. Do not assume the debt can simply be transferred or eliminated without lender approval.
Is a short sale better than foreclosure in Florida?
A short sale can be an alternative to foreclosure for some homeowners, but its financial and legal consequences vary. Discuss the situation with your lender and an appropriate professional before proceeding.
Should I talk to my lender before trying to sell my house?
Yes. Knowing the exact payoff amount, foreclosure status, deadlines, and lender requirements can help you make a more informed decision and avoid unnecessary delays.
How quickly can I sell my house in Pensacola for cash?
The timeline varies by buyer, property, title condition, and closing requirements. A cash transaction can sometimes move faster than a traditional financed sale, but homeowners should confirm the proposed closing date before relying on it to resolve a foreclosure deadline.
- Listing ID: 109259
- Country: USA
- City: Northwest Florida LLC